All Categories
Featured

Maximizing Indexed Universal Life Benefits for Retirement
Table of Contents
You are spending for permanence and guaranteed cash value, not just a survivor benefit. Larger entire life policies scale up roughly in percentage to the face amount. If your goal is pure earnings replacement, term life provides much more coverage per dollar; if your goal is ensured long-term coverage no matter how long you live, whole life is constructed for that.
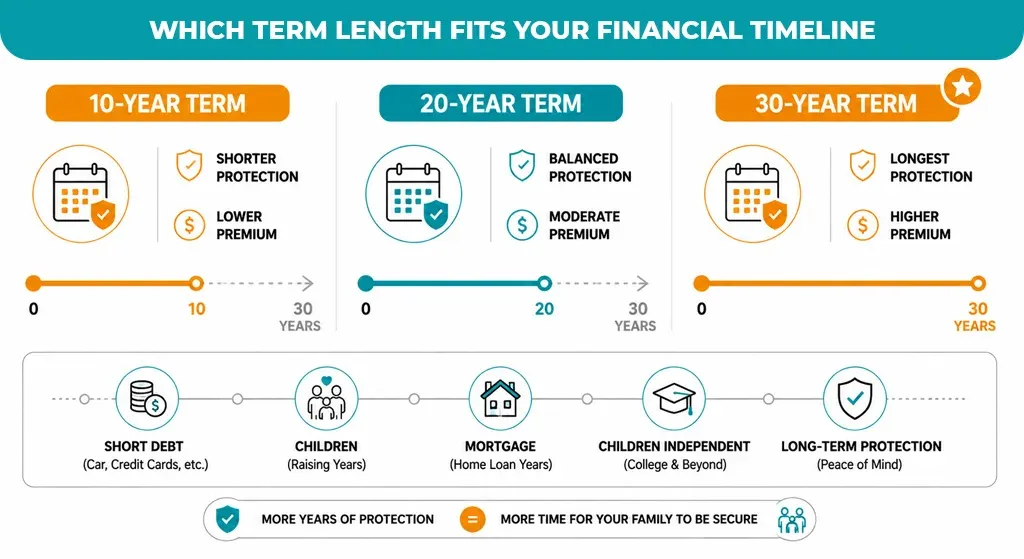
Below are common term life rates for elders a $250,000 10-year term policy (male, non-smoker): AgeMonthly PremiumAnnual Cost60$70$84065$120$1,44070$210$2,52075$380$4,560 A lot of providers cap term length as you age a 20-year term is extensively readily available at 60 but seldom at 70. Match the term to a particular need (a staying mortgage, a spouse's earnings gap).
An expert broker assists you discover the provider that treats your health most favorably. This is the most affordable time to purchase, even if your coverage needs are modest.
The Way Whole Life Insurance Protects Families in 2026
You can always include more coverage later on. SituationRecommended CoverageMarried, kids, home mortgage$750K-$1.5 MSingle moms and dad$500K-$1MHigh earner ($150K+)$1.5 M-$3MPersonal + key person protection 20-year level term if your kids are young.
SituationRecommended CoverageKids heading to college in 5-10 years$500K-$1M (match to remaining years)Big mortgage remainingCoverage matching balanceApproaching peak earning years10-15x income 15 or 20-year level term. If you already have a 30-year term from your 30s, you might have enough.
Kids may be independent, mortgage is shrinking, and retirement cost savings are growing.
Obtaining Individual Health Insurance Quotes Fast
SituationRecommended CoverageFinal expenditures only$15K-$25K entire life or burial insuranceSpouse earnings security$100K-$250K termLegacy/ inheritanceWhole life based upon desired bequestEstate tax planningConsult estate lawyer Final cost entire life for the majority of. 10-year term for specific short-term needs like a staying mortgage. Here is the real expense of procrastination: Buy at AgeMonthlyTotal Over 20 YearsExtra Expense vs.
And that assumes you remain healthy. If you establish a health condition while waiting, the boost is even bigger. The math is simple: buy now, pay less. Get a totally free life insurance quote and see exactly what protection costs at your age. What is the best age to buy life insurance coverage? The best age is as young as possible.
Insurance in Garden Grove CAA 25-year-old pays roughly half what a 35-year-old pays for the same coverage. Buying in your 20s locks in the least expensive rate for the longest period. How much does life insurance coverage boost by age? Rates boost about 8-10% each year in your 20s-30s, 10-15% per year in your 40s, and 15-20% each year in your 50s-60s.
Insurance in Garden Grove CAEnhancing Financial Security with Whole Life Insurance
Is it too late to purchase life insurance coverage at 60? What are entire life insurance coverage rates by age? Entire life is several times more expensive than term due to the fact that the protection is irreversible and builds money value.
Women pay approximately 10-20% less. Bigger entire life policies scale up from there. See the entire life chart below. What are common life insurance rates for elders? For a healthy senior, a $250,000 10-year term policy (male, non-smoker) costs approximately $70/month at age 60, $120/month at age 65, and $210/month at age 70.
Rates rise steeply with age, so applying quicker rather than later matters most in this bracket. Compare rates from top life insurance providers. In this article, we'll break down the various factors that influence life insurance expenses, how much you can expect to pay, and pointers for getting the best rates.
The purchasing a 20-year term policy for $250,000 in coverage. These terms describe various types of term life insurance policies. Life insurance tends to be more costly than disability insurance coverage because it offers a death advantage to recipients, which can be a considerable amount of money.

Latest Posts
Affordable Individual Health Insurance Quotes in the US
Why Term Insurance Builds Future Security
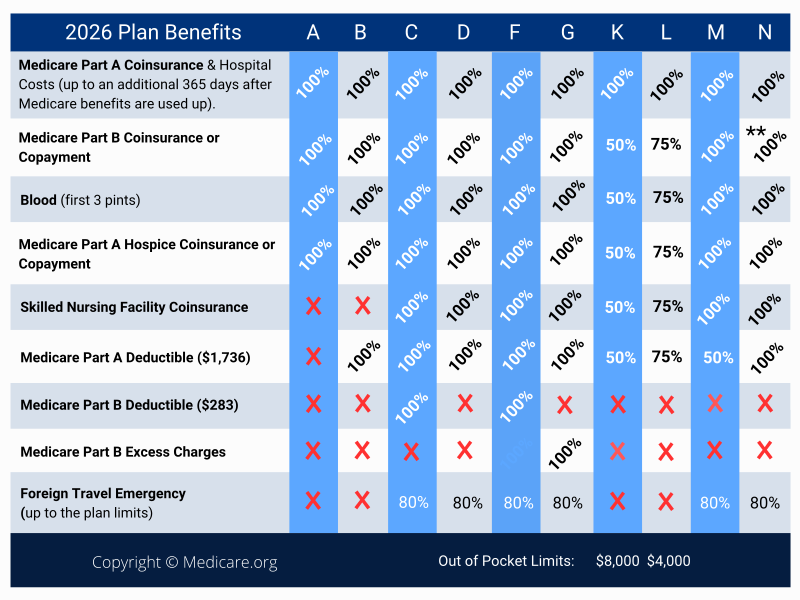
Selecting the Top 2026 Medicare Supplement Plan