All Categories
Featured


Upcoming Level Term Rates for Families
Table of Contents
This is due to the fact that ladies normally live longer than males. Insurance provider need to be sure that you don't take too numerous threats which if you do, you probably will pay more monthly. Things like race vehicle driving or skydiving. The term length of your insurance plan will likewise contribute in how much you pay monthly.
Insurance in Redlands CAYour health is the one element that makes everyone's premiums different. If you have a number of health conditions you can expect a greater premium than normal. Life insurance costs can also differ by state due to distinctions in regulations, cost of living, and other aspects. Below, we'll check out the average costs in a few states.
In Georgia, the same policy might cost around $20 to $30 per month for a healthy 30-year-old. Universal life insurance coverage in Texas can be more costly due to its long-lasting coverage and cash worth component. A healthy 30-year-old might pay around $100 to $150 each month for a $500,000 policy.
Obtaining Individual Health Insurance Quotes Online
Below is a table that describes a few life insurance rates by states. A lot of people require at least 10 times their yearly earnings in coverage, though 15 to 20 times your income gives your family a more powerful monetary cushion if you can manage it.
This will replace your earnings for your family by 10 years. , at 10x you must have. If you can manage it, at a licensed representative, I recommend choosing 15 to 20 times your annual wage so that your household can have if you pass away. The very best way to compute your life insurance coverage requires is to determine what your present financial scenario is, and what it would appear like if you weren't around.
The 3 primary types are level term, reducing term, and increasing term. Level term keeps everything fixed, decreasing term diminishes the survivor benefit with time, and increasing term raises it gradually. The main types of term life insurance are level term, decreasing term, and increasing term. Level term keeps premiums and death advantages fixed.
Increasing term gradually raises the death advantage, frequently to match inflation or increasing needs. Yes, life insurance deserves it for most people. It provides monetary security for your liked ones, covers debts, and can even work as an investment car in the case of whole life insurance coverage. Term life insurance coverage covers a death advantage paid to your beneficiaries, and can likewise help with funeral expenses, financial obligations, earnings replacement, and estate taxes.
Some policies include riders for terminal disease, unintentional death, or long-lasting care expenses. Life insurance coverage policies typically do not have deductibles.
The Way Whole Life Insurance Protects Families in 2026
Remaining healthy, stopping cigarette smoking, and selecting term over whole life are your greatest levers for cutting premiums, and comparing quotes from numerous providers locks in the very best rate. There are several methods to reduce your life insurance premiums. Maintaining a healthy lifestyle, giving up smoking, and selecting a term policy over an entire life policy can help in reducing expenses.
No, impairment insurance coverage and life insurance coverage serve different functions. Special needs insurance coverage offers earnings replacement if you become not able to work due to a disability, while life insurance offers a death advantage to your recipients.
No, life insurance is not needed by law in America, and there are no penalties for not having it. Having life insurance is extremely advised to make sure monetary security for your enjoyed ones.
Feel complimentary to use our. Now that you have a much better understanding of term life insurance coverage costs and the factors that influence them, it's time to take action.
Part D Enrollment Strategies for the 2026 Cycle
Term life insurance is usually better for many individuals due to its lower premiums and simple coverage. Entire life insurance offers lifelong coverage and a cash value component however is more expensive.

Latest Posts

Key Tips on 2026 Medicare Part D Enrollment
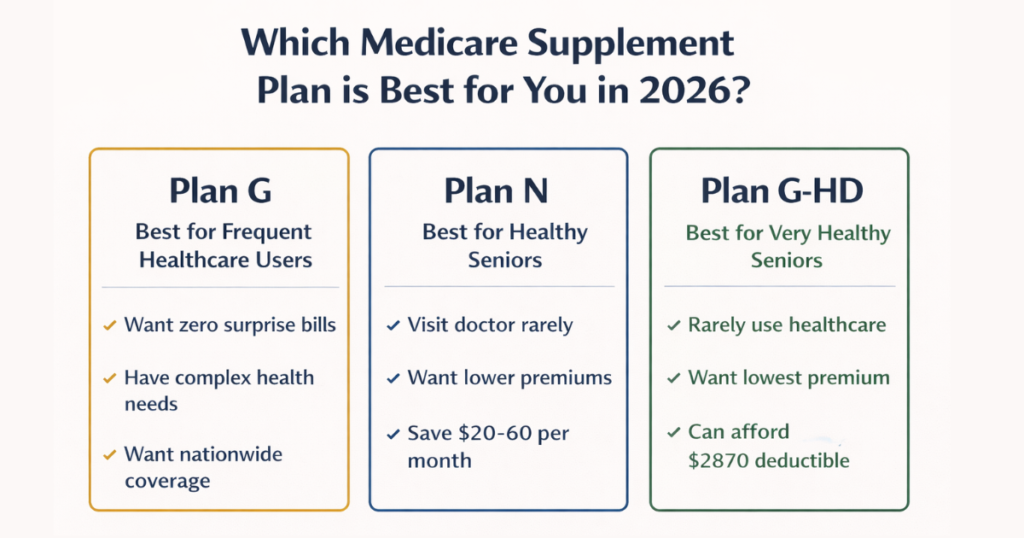
Selecting Your Top 2026 Medicare Supplement Plans
Choosing HMO or PPO Health Plans